
Expert Comment: COP17 delivered limited progress for nature - financing it remains unresolved
Almost four years ago, at COP15 in Montreal, countries agreed an ambitious set of global targets to halt and reverse nature loss by 2030. Yet, halfway between those commitments and the target deadline, the finance needed to protect the natural world remains far out of reach. Dr Hassan Aftab Sheikh, Research Fellow in Nature Finance at the Smith School of Enterprise and the Environment reflects on this year’s UN Biodiversity Conference, COP17 in Yerevan, and what it would take to close the financing gap.
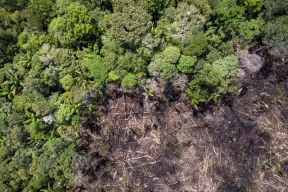

Every two years, diplomats, scientists, campaigners and businesses gather at a UN conference on Biological Diversity to take the temperature of the planet’s living systems. It is where countries agree the rules for protecting the variety of life on Earth, from coral reefs and rainforests to the bacteria in your gut. This year’s COP17 was held in Yerevan, the capital of Armenia.
My own research sits at the nexus of where nature meets finance. The first is finance: why private capital for nature has been so slow to arrive, and where public and concessional money (for example subsidised loans) should step in. This is the heart of Targets 18 and 19 set in Kunming-Montreal Global Biodiversity Framework in 2022, which call for redirecting harmful incentives and mobilising at least US$200 billion a year.
My second focus is nature credit markets, where biodiversity credits promise a new way to fund conservation, but depend on existing regulatory frameworks. The third is measuring nature where targets ask businesses to disclose their nature-related risks and for the best available data to be accessible. Neither can happen without metrics decision-makers can actually use.
I jumped in and out of the formal negotiating rooms. Like many researchers, I followed the process through side events and conversations in the Blue Zone.
“The atmosphere was energetic from representatives from businesses, civil society, and NGOs, but there wasn’t a strong presence of the capital providers. The focus was on whether countries are keeping the commitments to the 23 targets set in Montreal.”
The China Pavilion was impossible to miss. It was packed with events every day, and I joined their business and finance session. Their work on nature markets is moving from research into practical experiments, which is something I’d like to see more countries do. I also spent time at events run by the Taskforce on Nature-related Financial Disclosures (TNFD) which has grown quickly since its recommendations were published in 2023.
The current state of finance for nature
COP17’s global stocktake found that nearly 90% of countries have set national biodiversity targets, but fewer than half of those assessed are on track. Officially, about 18% of land and 10% of the oceans are protected. An important lever of restoring, protecting, and managing nature depends on the funding and financing available, and finance is the hardest part to deliver. Annual investment in nature protection, restoration and sustainable management is about US$200 billion. Estimates suggest it must reach US$542 billion a year by 2030. Based on those figures, the annual shortfall is roughly US$340 billion.
Why private capital stays away
Governments cannot close this gap alone, and the private sector has to be part of the answer. Most nature projects look too risky to investors. They are often new and unproven, their revenues are uncertain or delayed, and their payback periods are long.
Private nature-related finance grew from US$749 million in 2021 to US$4 billion in 2023. That is impressive growth from a small base over the last few years. Blended finance, where public or concessional money absorbs some of the risk to attract private investors, can help. Yet multilateral and development banks provide on average 57% of blended finance, rising to 73% in low-income countries. Public money is carrying most of the risk. In my view, concessional capital should be reserved for projects with no credible revenue model and not be used as a blanket subsidy.
Credit markets: promise and peril
Biodiversity credits, which allow a buyer to fund a verified gain for nature, were one of the most talked-about tools in this space. Their appeal is clear: they put a price on nature and give money a route to flow, but a credit is only as good as its ecological integrity.
In a recent paper, we proposed a framework for judging the integrity of individual credits and for governing whole markets. Without shared baselines, rigorous monitoring and independent verification, credits risk paying for gains that would have happened anyway, or for gains that never materialise. We cannot promise finance through such credits if the outcomes are not additional as promised.
The problem with counting nature
Behind all of this sits a practical conundrum. Economies can measure carbon with reasonable precision. Nature (encompassing biodiversity) is far harder to quantify. Most monitoring tools are fragmented, and many metrics rely on models or proxies and are not directly measured.
A metric that is useful to an investor may be of little use to a farm manager or a conservation ecologist. To solve this problem, we need to group metrics into “families” that link business activity, pressures on nature, the state of nature and the implications for business. Having followed TNFD’s development over the last few years, I have seen how it has progressed. However, there is still a lot of work to be done on how these metrics are ‘decision-useful’ to a financier or a business beyond being measured and disclosed.
What Yerevan delivered
So, what did Yerevan actually deliver? Negotiators finished with texts that nudge existing commitments under what was agreed in Montreal and Cali. Countries were ‘encouraged’ to speed up subsidy reform, even though an estimated US$2.4 trillion a year still flows into subsidies that harm nature. Emerging economies were ‘invited’ to help fund conservation. A compromise on resource mobilisation was reached, but it guarantees no new finance and Cali Fund which was estimated to mobilise USD 1 billion a year stand at $7,085.
The clearest progress happened outside the formal rooms, through the Friends of Target 18 coalition and the Yerevan Biodiversity Finance Challenge. Meanwhile, the Yerevan Pathway sets out a roadmap for 2026 to 2030 to guide national efforts for nature.
COPs can be disorienting, with dozens of events running at once, but they’re also useful to see how global ambitions are being translated into action. There are four years left before 2030, when the targets set in 2022 in Montreal are supposed to be met. Nature needs finance that flows into protection, restoration and management, outcomes that are genuinely additional, and metrics that connect ecology to decisions in financial institutions and business. None of this is glamorous, but all of it is necessary to protect our natural world.
For more information about this story or republishing this content, please contact [email protected].


